Stablecoins Are Moving From Trading Tools to Financial Infrastructure
Stablecoins are expanding from crypto trading into payments, settlement, treasury operations, and cross-border finance
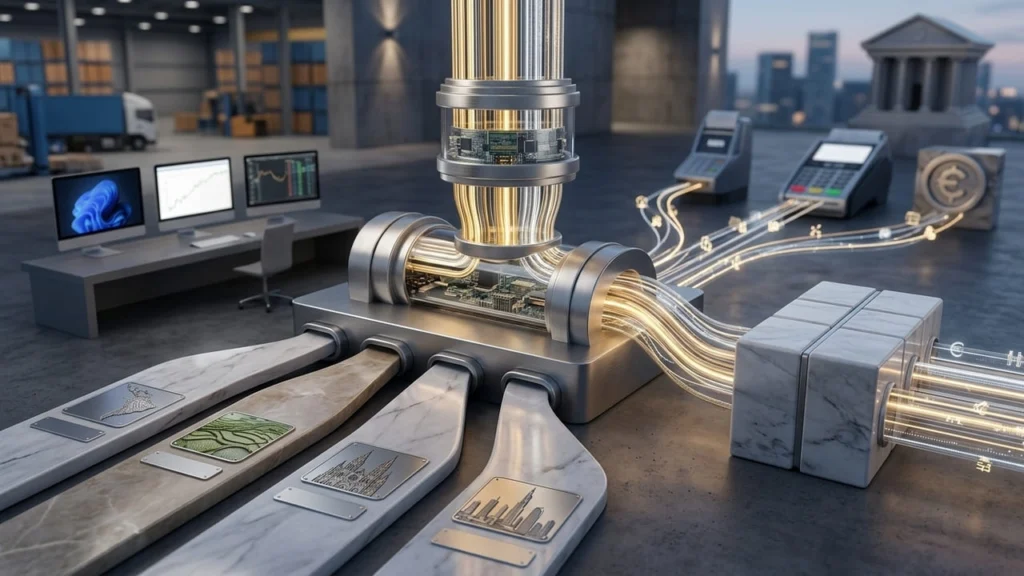
Stablecoins are no longer used primarily for crypto trading. Their role is expanding into the transfer and movement of funds between markets.
The case for stablecoins in payments, settlement, treasury operations, and cross-border transfers is becoming stronger as financial institutions explore blockchain-based infrastructure.
The key shift is structural rather than speculative.
Stablecoins can connect blockchain networks with banks, payment systems, and local currencies. That makes them potentially useful as financial infrastructure rather than simply as temporary parking places for traders.
Stablecoins Are Becoming Part of Institutional Finance
Institutional behavior shows why this broader shift deserves attention.
Bank of America reportedly reduced its MicroStrategy holdings from 3.97 million shares to 1.18 million. At the same time, its BlackRock ETHA position rose from 67,500 shares to about 1.98 million.
🚀 Bank of America Is Rotating From MSTR Into Ethereum
Bank of America made a notable move in Q2:
• MSTR holdings: 3.97M → 1.18M shares, down ~70%
• BlackRock ETHA: 67.5K → 1.98M shares, nearly 29x higher
• ETHA position value: ~$23.6MOne of the world’s largest banks is… pic.twitter.com/0qpUIo92YI
— Ethereum Daily (@ETH_Daily) August 18, 2026
That move should not be treated as proof of an Ethereum rotation or as direct evidence of institutional demand for stablecoin infrastructure. Still, the reported changes illustrate that institutional crypto exposure can extend across different assets and investment vehicles.
Ethereum is also more than a traded asset. It supports blockchain-based financial activity, including stablecoins, decentralized finance, and tokenized assets. Stablecoins operating on such networks can therefore generate transaction activity that is distinct from speculative demand for the native token.
The stronger argument is not that Ethereum will replace Bitcoin.
Instead, institutional interest is increasingly extending toward infrastructure-based use cases. Stablecoins are one of the clearest examples of that broader category.
Stablecoin Yield Is Really a Competition Question
The debate over stablecoin yield is often framed around banking risk. However, it can also be viewed as a question of competition for customer funds.
Yield-bearing digital dollars could compete with bank deposits if users begin moving part of their liquid savings toward stablecoin-based products. The scale of that competition remains uncertain, particularly because stablecoin use varies significantly by market and application.
Community banks were already facing structural pressures before stablecoins became widely used. Regulatory costs, technology spending, consolidation, and scale advantages had already changed the sector. Stablecoins did not create those pressures.
Restricting stablecoin yield could therefore protect some existing deposit models without addressing the underlying challenges facing community banks. Larger banks would still retain many of their cost and scale advantages, while smaller lenders would continue to face broader operating pressures.
That’s not the end of the need for stablecoin regulation. Quality, disclosure, liquidity, reserve management, and consumer protection remain important. Regulation should address those risks without unnecessarily restricting competition between financial products.
Team Warren’s Stablecoin Crusade Protects Big Banks, Not Community Banks
The war on stablecoin yield is being sold as a defense of community banks. It is nothing of the sort. It is the latest example of Team Warren blaming a new competitor for damage inflicted by Washington’s… https://t.co/dbIQtKU4EP
— James E. Thorne (@DrJStrategy) August 18, 2026
The utility of stablecoins could increase further if they become more integrated into payments, settlement, and other financial services. That does not mean bank deposits would need to disappear.
Even limited competition could encourage financial institutions to improve the efficiency of their deposit, payment, and settlement operations.
Global Stablecoins Will Still Depend on Local Systems
Stablecoins can move across borders, but financial systems remain largely national.
Governments still control access to banking, foreign exchange, identity requirements, and payment licenses. That means stablecoin adoption is unlikely to follow a single global model.
Brazil has brought virtual-asset services into parts of its foreign-exchange framework.
Vietnam is developing a regulated crypto market while maintaining restrictions on crypto payments. The Philippines has also maintained limits affecting new virtual-asset service provider licenses.
I agree that stablecoins are becoming an important global rail for moving money. I see the implications for borders somewhat differently.
Stablecoins may change how money moves but sovereign financial systems still determine how to integrate them, not the other way around. I… https://t.co/oG3SeUoHqK
— Jack Zhang (@awxjack) August 17, 2026
These differences illustrate the main challenge for stablecoin growth. The technology can operate globally, but access to financial systems remains local. Businesses still need banking relationships, liquidity, fiat conversion, and regulated payment channels to connect stablecoins with conventional finance.
Therefore, stablecoins are unlikely to replace national financial systems outright. Their more plausible long-term role is to connect parts of those systems more efficiently.
That makes interoperability more important than disruption.
The long-term test is whether stablecoins remain useful when crypto trading activity declines. If businesses continue using them for settlement, treasury operations, payments, or cross-border transfers, their infrastructure role becomes clearer.
That is the more important shift taking place. Stablecoins are moving beyond their role in crypto trading and toward potential use across the broader financial system. Their future will depend on usefulness, regulation, and integration with existing financial infrastructure.
Samuel Munene
I’ve built my writing career around following the ideas, projects, and people shaping the crypto and Web3 space. Blockchain technology interests me not only as a financial innovation, but also for the way it is being applied across different industries.
More from Samuel Munene →This article is for information only and is not investment advice. We report under our Editorial Policy; to flag an error, see our Corrections Policy.