Solana’s Institutional Push Is Shifting From Transaction Speed to Financial Infrastructure
Solana DvP links tokenized assets and payments through atomic settlement, adding escrow and custodian support to institutional finance
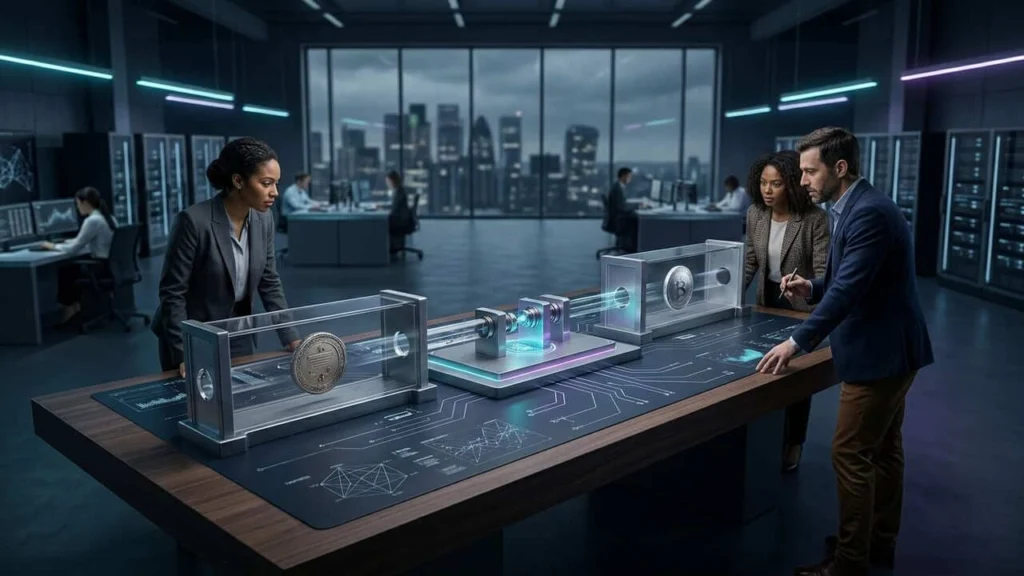
Solana is expanding its institutional blockchain strategy beyond transaction speed, introducing settlement infrastructure designed to support tokenized securities, digital payments, and traditional financial institutions. The shift follows the Solana Foundation’s October 6 launch of a delivery-versus-payment (DvP) program, highlighted in its October 8 developer changelog.
Its design links asset delivery and payment within one transaction, addressing a practical concern for financial institutions. Both transfers must be completed together, preventing one party from delivering without receiving the agreed consideration.
Solana DvP Links Asset Transfers Through Escrow
Each trade starts with agreed asset amounts, payment amounts, participants, and a settlement deadline. The program creates separate escrow accounts where both parties deposit their tokens before either side receives payment.
A designated authority, such as a bank or custodian, signs the settlement instruction. If either transfer fails, neither transfer occurs, protecting both parties against incomplete exchange. Parties retain access to their deposits until settlement. Either can reclaim its tokens, and the authority can cancel an unsettled trade.
Those procedures resemble traditional securities settlement controls, but the final exchange occurs in a single blockchain transaction. The arrangement addresses settlement mechanics rather than the number of transactions a network processes.
Solana DvP supports SPL tokens and qualifying Token-2022 assets, including selected issuer controls. Transfer hooks can enforce restrictions on token movements, subject to individual token configurations and issuer requirements.
However, its documentation excludes extensions covering transfer fees, interest-bearing tokens, and nontransferable assets. Issuers must therefore review token features before attempting settlement.
Custodians Connect Tokenized Assets With Payments
Custodians can fund an escrow using an ordinary token transfer. They do not need to deploy their own program to complete this step. However, participants must review the recorded terms before depositing funds, as creating a trade does not constitute agreement. The settlement authority also verifies those terms before authorizing payment and delivery.
The system follows the Solana Developer Platform, which launched in March with tools for financial institutions. Its issuance and payment modules cover tokenized assets, stablecoins, and related financial transfers.
The platform incorporates custody, wallet, and compliance infrastructure partners. The DvP program addresses another stage: exchanging an issued token for an agreed payment. Token issuance alone does not settle a securities trade.
Buyers and sellers still need to exchange assets and payment under agreed conditions. Solana’s program supports two onchain token transfers but cannot include an ordinary bank payment in that exchange. Any off-chain payment requires separate settlement and reconciliation.
Institutional Use Extends Beyond Transaction Speed
The DvP program excludes order matching, price discovery, identity checks, and trade netting. Participants agree on terms outside the program before recording a bilateral transaction. A settlement authority must then approve completion with its designated signature. The program does not automatically settle trades without that authorization.
J.P. Morgan supplied input about traditional securities settlement requirements during the program’s development. However, the bank did not develop, operate, endorse, or guarantee the infrastructure.
Solana’s technical documentation identifies Cantina as the auditor, while the Foundation reports external security reviews. Privacy features remain planned rather than available in the current version of the program.
Solana DvP therefore provides settlement logic without replacing existing financial market functions. The Foundation is seeking design partners and early participants before its broader production release.
Institutions must still assess custody arrangements, token restrictions, and their own settlement obligations. Those operational requirements form the clearest distinction between processing transactions quickly and completing institutional financial trades
Brenda Kanana
My name is Brenda Kanana, and I’m a crypto journalist passionate about making the world of cryptocurrency engaging and accessible to readers. I cover a wide range of topics, including crypto news, opinion pieces, technical analysis, and price predictions.
More from Brenda Kanana →This article is for information only and is not investment advice. We report under our Editorial Policy; to flag an error, see our Corrections Policy.