
Memecoins have usually been defined by their lack of cash flows, formal ownership rights and practical use. U.S. regulators have now opened a different route by recognizing that a memecoin can begin without functionality and later become a digital commodity. That creates a new incentive for token teams to think about utility as part of legal design. The harder question is whether utility will still be built mainly for users, or increasingly with classification in mind.
Utility Is Becoming Part of Token Design
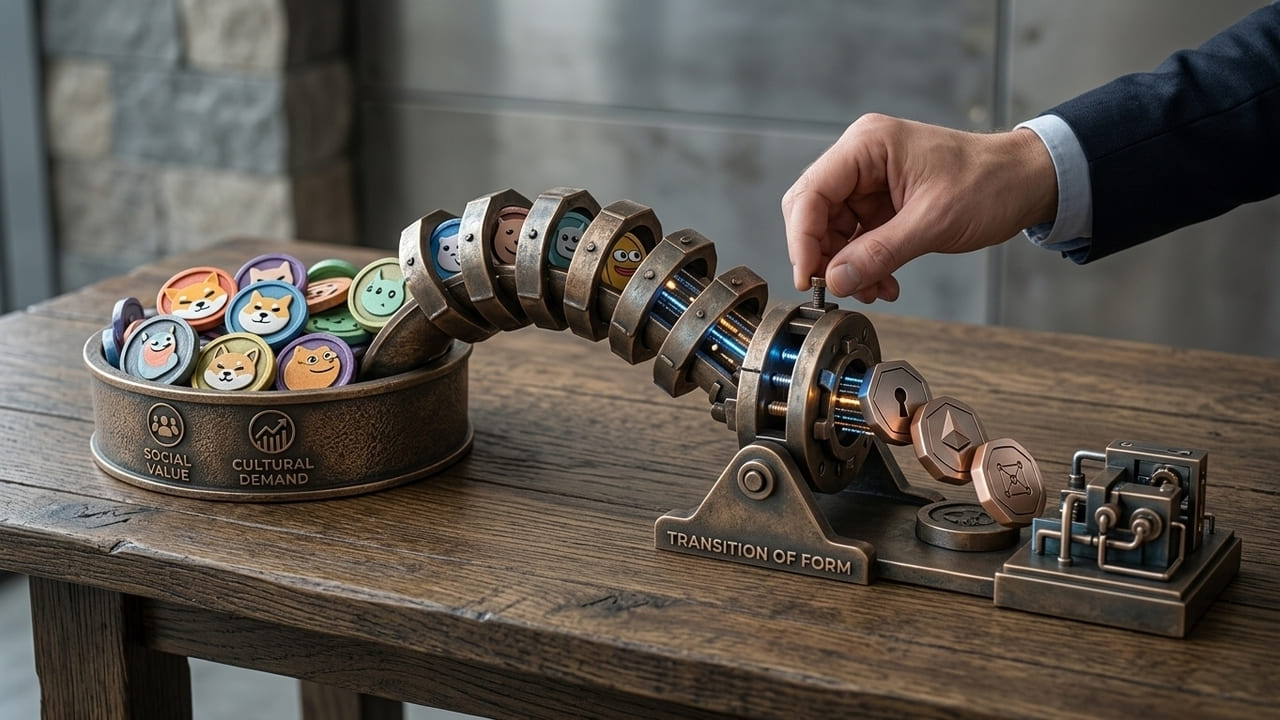
The SEC and CFTC’s March 2026 interpretation divides crypto assets into five categories, including digital commodities, digital collectibles and digital tools. Memecoins generally fit within digital collectibles when their value comes from social, cultural or entertainment demand rather than a promoter’s essential managerial work.
The interpretation also allows that status to change. A memecoin launched without functionality can later become a digital commodity if it becomes functional within an associated crypto system. That matters as classification is no longer tied only to the token’s identity when trading begins. Development after launch can change how regulators view the asset.
A Legal Incentive May Sit Behind New Features
This creates an obvious design incentive. If functionality can support a different regulatory category, projects may have reasons to add access rights, network uses or other programmed features beyond improving the product. Utility could become part of the legal architecture surrounding a token.
That does not make such development artificial by default. Crypto networks often add functions as communities and infrastructure mature. The regulatory change is that those choices may now carry a second purpose. Product teams and lawyers could assess each feature based on user needs and its potential effect on the token’s regulatory status.
The definition of a digital commodity makes that distinction important. The agencies describe such an asset as deriving value from a functional crypto system and market supply and demand, rather than expected profits from another party’s essential managerial efforts.
A feature therefore needs to connect the token to actual system use, rather than simply give the project a new label.
Promised Utility Can Work Against a Project
The strategy also contains a contradiction. The same interpretation says a non-security crypto asset can become subject to an investment contract when buyers reasonably expect profits from an issuer’s essential managerial efforts. How a token is marketed can therefore matter as much as the finished feature.
That creates a problem for projects selling a future vision. The SEC says detailed promises involving functionality, development milestones, timelines, personnel, funding and expected holder profits can support an expectation of profit. Such representations can connect a non-security token to an investment contract even when the underlying asset is not itself a security.
Also, the regulatory agencies specifically describe a memecoin that launches without promises of future functionality and only later becomes functional. That scenario differs from selling a token while asking buyers to rely on a team to build the system that may increase its value.
Regulators May Need to Separate Use From Labeling
The framework could create a harder test for regulators. A feature can be real while still being designed partly for legal reasons. Token-gated communities, airdrop access or membership functions can give holders something to do, yet they do not automatically show that a token derives its value from a functional crypto system.
The SEC’s 2025 staff statement had already described typical memecoins as assets bought for entertainment, social interaction and cultural purposes. It also warned that simply labeling something a memecoin would not protect a transaction that otherwise falls within securities law.
That staff statement carried no legal force, and the March 2026 interpretation says the Commission’s newer views supersede earlier staff positions on the covered subjects.
Utility therefore looks less like a regulatory shortcut than a new form of legal strategy. Projects now have clearer reasons to consider functionality, launch structure and public promises together. Yet adding a feature later cannot rewrite the economic facts surrounding an earlier sale.