
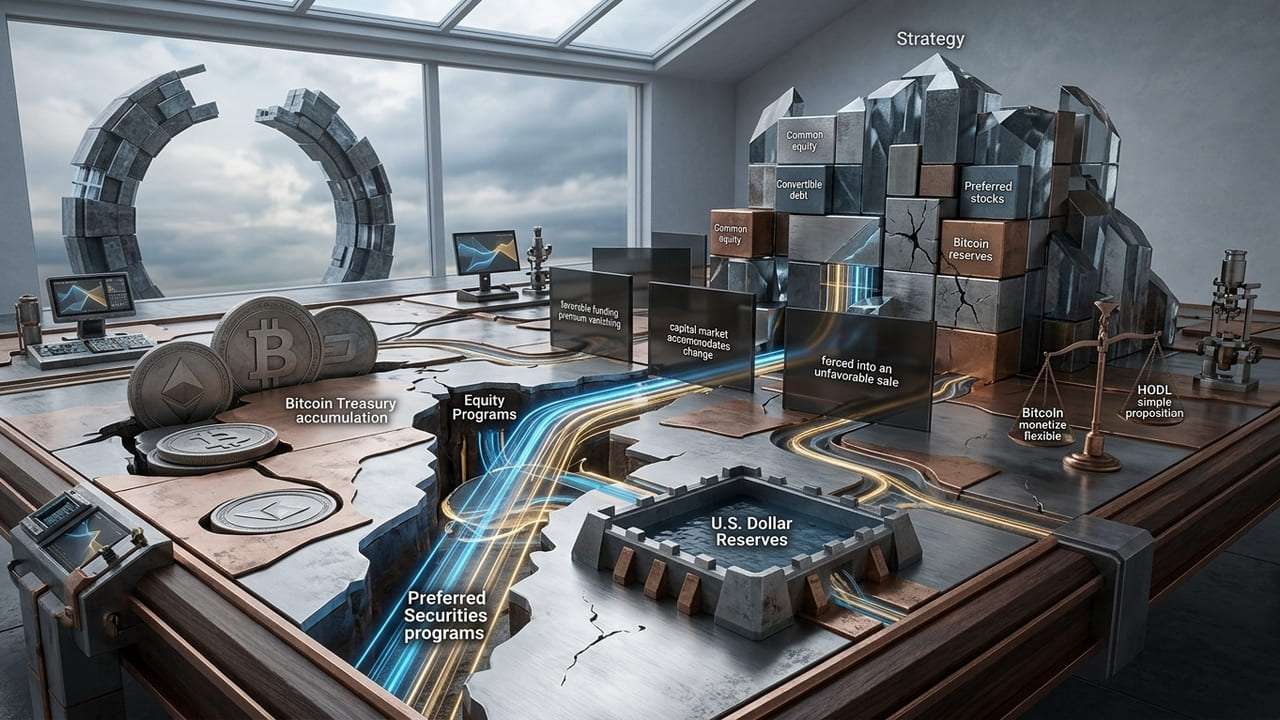
The premium that funded two years of accumulation has vanished across much of the sector. Strategy built the most complete version of the model reserves, a real preferred stack, and the discipline to sell when it has to which is exactly why its balance sheet is the one now being tested.
The Bitcoin treasury strategy began with a straightforward proposition: raise capital, buy Bitcoin and hold it.
That approach has evolved considerably. As institutional interest in Bitcoin has grown, publicly traded companies have increasingly treated BTC not simply as an investment, but as the foundation of a broader corporate-finance strategy.Yet the model is approaching an important test.
What happens when a Bitcoin treasury company can no longer rely on issuing new capital to fund additional purchases?
That question goes to the heart of the model’s long-term sustainability.
From Bitcoin Holdings to Financial Architecture
Strategy has become one of the most developed examples of the corporate Bitcoin treasury model.
The company has moved well beyond simply holding Bitcoin on its balance sheet. It has built a complex financial structure involving common equity, preferred securities, convertible debt, cash reserves and Bitcoin itself.
By July 26, 2026, Strategy reported holding 843,775 BTC. During the year, it had also raised $17.06 billion through equity programs and $7.53 billion through its STRC preferred-stock program, while maintaining a $3.75 billion U.S. dollar reserve for dividends and interest.
The significance is not simply the size of Strategy’s Bitcoin holdings. It is the financial infrastructure built around them.
The company has also established mechanisms through which Bitcoin can be monetized when liquidity is required.That distinction matters.
For years, the dominant Bitcoin investment philosophy has been summarized by one word: HODL. But a public company has obligations that an individual Bitcoin holder does not. It must service debt, meet preferred-dividend obligations, fund operations and manage shareholder expectations.
Holding an asset is therefore only one part of the equation.
The Bitcoin treasury model looks particularly attractive when Bitcoin is appreciating and investors are willing to provide companies with fresh capital.
A company can issue shares, raise debt or sell preferred securities, then deploy the proceeds into Bitcoin. If BTC appreciates faster than the company’s financing costs and other obligations, the strategy can create substantial value for shareholders.
But the equation changes when capital markets become less accommodating.
If a company’s share price falls, issuing new equity can become increasingly dilutive. If borrowing costs rise, debt becomes more expensive. If Bitcoin stagnates or declines, the company may no longer have the same flexibility to use its valuation as a source of financing.
That is where the distinction between a Bitcoin holding strategy and a genuine capital structure becomes critical.
HODL Is Not Enough
Strategy’s experience illustrates this tension.
During the second quarter, the company reported an $8.32 billion loss on digital assets, including an $8.31 billion unrealized loss. Yet the company continued managing its broader financial structure, including its debt, preferred securities and dollar reserves.
This is an important feature of the model.
A treasury company cannot simply say that Bitcoin will eventually recover. It has financial commitments that exist regardless of the market’s short-term direction.
The question is therefore not necessarily whether the company should sell Bitcoin.
The more important question is whether it has enough liquidity and financial flexibility to avoid being forced into an unfavorable sale.
That requires a capital structure capable of functioning across different market conditions.
The Next Phase of the Treasury Model
This may become the defining challenge for the next generation of Bitcoin treasury companies.
Accumulating BTC is relatively easy when investors are enthusiastic and capital is readily available. Building a financial structure that can withstand tighter liquidity, higher financing costs and prolonged Bitcoin volatility is considerably harder.
Strategy’s evolution provides one possible blueprint, combining Bitcoin reserves with dollar liquidity, debt and several classes of preferred securities.
Whether that model ultimately proves sustainable is still an open question. But the direction of the industry is becoming clearer.
Investors may increasingly need to look beyond the headline number of Bitcoin held on a company’s balance sheet.
The more important questions could be how that Bitcoin was financed,what obligations sit ahead of it, how much liquidity the company controls and what happens if access to capital markets weakens.
But HODLing alone is not a capital structure.
The companies that endure through the next stage of the Bitcoin treasury cycle will need to demonstrate that their financial architecture works not only when Bitcoin is rising and capital is abundant, but also when the market stops making accumulation easy.